ads1

Tampilkan postingan dengan label Fiscal Theory. Tampilkan semua postingan

Rabu, 05 Juli 2023

Fiscal inflation and interest rates


Economics is about solving lots of little puzzles. At a July 4th party, a super smart friend -- not a macroeconomist -- posed a puzzle I should have understood long ago, prompting me to understand my own models a little better. 

How do we get inflation from the big fiscal stimulus of 2020-2021, he asked? Well, I answer, people get a lot of government debt and money, which they don't think will be paid back via higher future taxes or lower future spending. They know inflation or default will happen sooner or later, so they try to get rid of the debt now while they can rather than save it. But all we can do collectively is to try to buy things, sending up the price level, until the debt is devalued to what we expect the government can and will pay. 

OK, asked my friend, but that should send interest rates up, bond prices down, no? And interest rates stayed low throughout, until the Fed started raising them. I mumbled some excuse about interest rates never being very good at forecasting inflation, or something about risk premiums, but that's clearly unsatisfactory. 

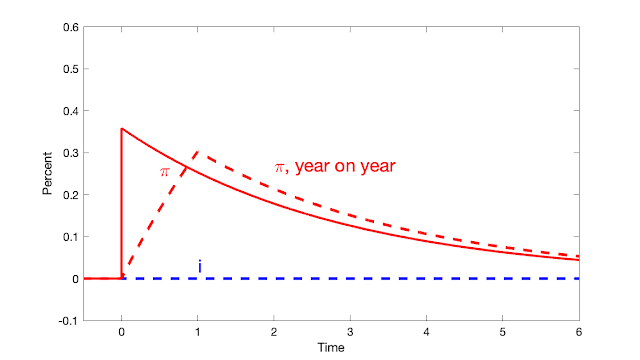
Of course, the answer is that interest rates do not need to move. The Fed controls the nominal interest rate. If the Fed keeps the short term nominal interest rate constant, then nominal yields of all bonds stay the same, while fiscal inflation washes away the value of debt. I should have remembered my own central graph: 

This is the response of the standard sticky price model to a fiscal shock -- a 1% deficit that is not repaid by future surpluses -- while the Fed keeps interest rates constant. The solid line is instantaneous inflation, while the dashed line gives inflation measured as percent change from a year ago, which is the common way to measure it in the data. 

There you have it: The fiscal shock causes inflation, but since the nominal interest rate is fixed by the Fed, it goes nowhere, and long term bonds (in this linear model with the expectations hypothesis) go nowhere too. 

OK for the result, but how does it work? What about the intuition, that seeing inflation coming we should see higher interest rates? Let's dig deeper. 

Start with the simplest model, one-period debt and flexible prices. Now the model comes down to, nominal debt / price level = present value of surpluses, \[\frac{B_{t-1}}{P_t} = E_t \sum_{j=0}^\infty \beta^j s_{t+j}.\] (If you don't like equations, just read the words. They will do.) With a decline in the present value of surpluses, the value of debt coming due today (top left) can't change, so the price level must rise. The price of debt coming due is fixed at 1, so its relative price can't fall and its interest rate can't rise. Or, this model describes a price level jump. We get bad fiscal news, people try to spend their bonds, the price level jumps unexpectedly up, (\(P_t\) jumps up relative to \(E_{t-1}P_t\), but there is no further inflation, no rise in expected inflation so the interest rate \(i_t = r+ E_t \pi_{t+1}\) doesn't change. 

Ok, fine, you say, but that's one period, overnight debt, reserves at the Fed only. What about long term bonds? When we try to sell them, their prices can go down and interest rates go up, no? No, because if the Fed holds the nominal interest rate constant, their nominal prices don't change. With long term bonds, the basic equation becomes market value of nominal debt / price level = expected value of surpluses, \[\frac{\sum_{j=0}^\infty Q_t^{(j)} B_{t-1}^{(j)}}{P_t} = E_t \sum_{j=0}^\infty \beta^j s_{t+j}.\] Here, \(Q_t^{(j)}\) is the price of \(j\) period debt at time \(t\), and \(B_{t-1}^{(j)}\) is the face value of debt at the beginning of time \(t\) that matures in time \(t+j\). (\(Q_t^{(j)}=1/[1+y^{(j)}_t)]^j\) where \(y^{(j)}_t\) is the yield on \(j\) period debt; when the price goes down the yield or long-term interest rate goes up. )

So, my smart friend notices, when the present value of surpluses declines, we could see nominal bond prices \(Q\) on top fall rather than the price level \(P\) on the bottom rise.  But we don't, because again, the Fed in this conceptual exercise keeps the nominal interest rate fixed, and so long term bond prices don't fall. If the \(Q\) don't fall, the \(P\) must rise. 

The one-period price level jump is not realistic, and the above graph plots what happens with sticky prices. (This is the standard continuous time new-Keynesian model.) The intuition is the same, but drawn out. The sum of future surpluses has fallen. People try to sell bonds, but with a constant interest rate the nominal price of long term bonds cannot fall. So, they try to sell bonds of all maturities, pushing up the price of goods and services. With sticky prices, this takes time; the price level slowly rises as inflation exceeds the nominal interest rate. A drawn out period of low real interest rates slowly saps the value of bondholder's wealth. In present value terms, the decline in surpluses is initially matched by a low real discount rate. Yes, there is expected inflation. Yes, long-term bondholders would like to escape it. But there is no escape: real rates of return are low on all bonds, short-term and long term. 

So, dear friend, we really can have a period of fiscal inflation, with no change in nominal interest rates. Note also that the inflation eventually goes away, so long as there are no more fiscal shocks, even without the Fed raising rates. That too seems a bit like our reality. This has all been in my own papers for 20 years. It's interesting how hard it can be to apply one's own models right on the spot. Maybe it was the great drinks and ribs. 


Senin, 12 Juni 2023

Papers: Dew-Becker on Networks


I've been reading a lot of macro lately. In part, I'm just catching up from a few years of book writing. In part,  I want to understand inflation dynamics, the quest set forth in "expectations and the neutrality of interest rates," and an  obvious next step in the fiscal theory program. Perhaps blog readers might find interesting some summaries of recent papers, when there is a great idea that can be summarized without a huge amount of math. So, I start a series on cool papers I'm reading. 

Today: "Tail risk in production networks" by Ian Dew-Becker, a beautiful paper. A "production network" approach recognizes that each firm buys from others, and models this interconnection. It's a hot topic for lots of reasons, below.  I'm interested because prices cascading through production networks might induce a better model of inflation dynamics. 

(This post uses Mathjax equations. If you're seeing garbage like [\alpha = \beta] then come back to the source  here.) 

To Ian's paper: Each firm uses other firms' outputs as inputs. Now, hit the economy with a vector of productivity shocks. Some firms get more productive, some get less productive. The more productive ones will expand and lower prices, but that changes everyone's input prices too. Where does it all settle down? This is the fun question of network economics. 

Ian's central idea: The problem simplifies a lot for large shocks. Usually when problems are complicated we look at first or second order approximations, i.e. for small shocks, obtaining linear or quadratic ("simple") approximations. 


On the x axis, take a vector of productivity shocks for each firm, and scale it up or down. The x axis represents this overall scale. The y axis is GDP. The right hand graph is Ian's point: for large shocks, log GDP becomes linear in log productivity -- really simple. 

Why? Because for large enough shocks, all the networky stuff disappears. Each firm's output moves up or down depending only on one critical input. 

To see this, we have to dig deeper to complements vs. substitutes. Suppose the price of an input goes up 10%. The firm tries to use less of this input. If the best it can do is to cut use 5%, then the firm ends up paying 5% more overall for this input, the "expenditure share" of this input rises. That is the case of "complements." But if the firm can cut use of the input 15%, then it pays 5% less overall for the input, even though the price went up. That is the case of "substitutes." This is the key concept for the whole question: when an input's price goes up, does its share of overall expenditure go up (complements) or down (substitutes)? 

Suppose inputs are complements. Again, this vector of technology shocks hits the economy. As the size of the shock gets bigger, the expenditure of each firm, and thus the price it charges for its output, becomes more and more dominated by the one input whose price grows the most. In that sense, all the networkiness simplifies enormously. Each firm is only "connected" to one other firm. 

Turn the shock around. Each firm that was getting a productivity boost now gets a productivity reduction. Each price that was going up now goes down. Again, in the large shock limit, our firm's price becomes dominated by the price of its most expensive input. But it's a different input.  So, naturally, the economy's response to this technology shock is linear, but with a different slope in one direction vs. the other. 

Suppose instead that inputs are substitutes. Now, as prices change, the firm expands more and more its use of the cheapest input, and its costs and price become dominated by that input instead. Again, the network collapsed to one link.  

Ian: "negative productivity shocks propagate downstream through parts of the production process that are complementary (\(\sigma_i < 1\)), while positive productivity shocks propagate through parts that are substitutable (\(\sigma_i > 1\)). ...every sector’s behavior ends up driven by a single one of its inputs....there is a tail network, which depends on \(\theta\) and in which each sector has just a single upstream link."

Equations: Each firm's production function is (somewhat simplifying Ian's (1)) \[Y_i = Z_i L_i^{1-\alpha} \left( \sum_j A_{ij}^{1/\sigma} X_{ij}^{(\sigma-1)/\sigma} \right)^{\alpha \sigma/(\sigma-1)}.\]Here \(Y_i\) is output, \(Z_i\) is productivity, \(L_i\) is labor input, \(X_{ij}\) is how much good j firm i  uses as an input, and \(A_{ij}\) captures how important each input is in production. \(\sigma>1\) are substitutes, \(\sigma<1\) are complements. 

Firms are competitive, so price equals marginal cost, and each firm's price is \[ p_i = -z_i + \frac{\alpha}{1-\sigma}\log\left(\sum_j A_{ij}e^{(1-\sigma)p_j}\right).\; \; \; (1)\]Small letters are logs of big letters.  Each price depends on the prices of all the inputs, plus the firm's own productivity.  Log GDP, plotted in the above figure is \[gdp = -\beta'p\] where \(p\) is the vector of prices and \(\beta\) is a vector of how important each good is to the consumer. 

In the case \(\sigma=1\) (1)  reduces to a linear formula. We can easily solve for prices and then gdp as a function of the technology shocks: \[p_i = - z_i + \sum_j A_{ij} p_j\] and hence \[p=-(I-\alpha A)^{-1}z,\]where the letters represent vectors and matrices across \(i\) and \(j\). This expression shows some of the point of networks, that the pattern of prices and output reflects the whole network of production, not just individual firm productivity. But with \(\sigma \neq 1\) (1) is nonlinear without a known closed form solution. Hence approximations. 

You can see Ian's central point directly from (1). Take the \(\sigma<1\) case, complements. Parameterize the size of the technology shocks by a fixed vector \(\theta = [\theta_1, \ \theta_2, \ ...\theta_i,...]\) times a scalar \(t>0\), so that \(z_i=\theta_i \times t\). Then let \(t\) grow keeping the pattern of shocks \(\theta\) the same. Now, as the \(\{p_i\}\) get larger in absolute value, the term with the greatest \(p_i\) has the greatest value of \( e^{(1-\sigma)p_j} \). So, for large technology shocks \(z\), only that largest term matters, the log and e cancel, and \[p_i \approx -z_i + \alpha \max_{j} p_j.\] This is linear, so we can also write prices as a pattern \(\phi\) times the scale \(t\), in the large-t limit \(p_i = \phi_i t\),  and  \[\phi_i =  -\theta_i + \alpha \max_{j} \phi_j.\;\;\; (2)\] With substitutes, \(\sigma<1\), the firm's costs, and so its price, will be driven by the smallest (most negative) upstream price, in the same way. \[\phi_i \approx -\theta_i + \alpha \min_{j} \phi_j.\] 
To express gdp scaling with \(t\), write \(gdp=\lambda t\), or when you want to emphasize the dependence on the vector of technology shocks, \(\lambda(\theta)\). Then we find gdp by \(\lambda =-\beta'\phi\). 

In this big price limit, the \(A_{ij}\) contribute a constant term, which also washes out. Thus the actual "network" coefficients stop mattering at all so long as they are not zero -- the max and min are taken over all non-zero inputs. Ian: 
...the limits for prices, do not depend on the exact values of any \(\sigma_i\) or \(A_{i,j}.\) All that matters is whether the elasticities are above or below 1 and whether the production weights are greater than zero. In the example in Figure 2, changing the exact values of the production parameters (away from \(\sigma_i = 1\) or \(A_{i,j} = 0\)) changes...the levels of the asymptotes, and it can change the curvature of GDP with respect to productivity, but the slopes of the asymptotes are unaffected.
...when thinking about the supply-chain risks associated with large shocks, what is important is not how large a given supplier is on average, but rather how many sectors it supplies...
For a full solution, look at the (more interesting) case of complements, and suppose every firm uses a little bit of every other firm's output, so all the \(A_{ij}>0\). The largest input  price in (2) is the same for each firm \(i\), and you can quickly see then that the biggest price will be the smallest technology shock. Now we can solve the model for prices and GDP as a function of technology shocks: \[\phi_i \approx -\theta_i - \frac{\alpha}{1-\alpha} \theta_{\min},\] \[\lambda \approx  \beta'\theta + \frac{\alpha}{1-\alpha}\theta_{\min}.\] We have solved the large-shock approximation for prices and GDP as a function of technology shocks. (This is Ian's example 1.) 

The graph is concave when inputs are complements, and convex when they are substitutes. Let's do complements. We do the graph to the left of the kink by changing the sign of \(\theta\).  If the identity of \(\theta_{\min}\) did not change, \(\lambda(-\theta)=-\lambda(\theta)\) and the graph would be linear; it would go down on the left of the kink by the same amount it goes up on the right of the kink. But now a different \(j\) has the largest price and the worst technology shock. Since this must be a worse technology shock than the one driving the previous case, GDP is lower and the graph is concave.  \[-\lambda(-\theta) = \beta'\theta + \frac{\alpha}{1-\alpha}\theta_{\max} \ge\beta'\theta + \frac{\alpha}{1-\alpha}\theta_{\min} = \lambda(\theta).\] Therefore  \(\lambda(-\theta)\le-\lambda(\theta),\) the left side falls by more than the right side rises. 

Does all of this matter? Well, surely more for questions when there might be a big shock, such as the big shocks we saw in a pandemic, or big shocks we might see in a war. One of the big questions that network theory asks is, how much does GDP change if there is a technology shock in a particular industry? The \(\sigma=1\) case in which expenditure shares are constant gives a standard and fairly reassuring result: the effect on GDP of a shock in industry i is given by the ratio of i's output to total GDP. ("Hulten's theorem.") Industries that are small relative to GDP don't affect GDP that much if they get into trouble. 

You can intuit that constant expenditure shares are important for this result. If an industry has a negative technology shock, raises its prices, and others can't reduce use of its inputs, then its share of expenditure will rise, and it will all of a sudden be important to GDP. Continuing our example, if one firm has a negative technology shock, then it is the minimum technology, and [(d gdp/dz_i = \beta_i + \frac{\alpha}{1-\alpha}.\] For small firms (industries) the latter term is likely to be the most important.  All the A and \(\sigma\) have disappeared, and basically the whole economy is driven by this one unlucky industry and labor.   

Ian: 
...what determines tail risk is not whether there is granularity on average, but whether there can ever be granularity – whether a single sector can become pivotal if shocks are large enough.
For example, take electricity and restaurants. In normal times, those sectors are of similar size, which in a linear approximation would imply that they have similar effects on GDP. But one lesson of Covid was that shutting down restaurants is not catastrophic for GDP, [Consumer spending on food services and accommodations fell by 40 percent, or $403 billion between 2019Q4 and 2020Q2. Spending at movie theaters fell by 99 percent.] whereas one might expect that a significant reduction in available electricity would have strongly negative effects – and that those effects would be convex in the size of the decline in available power. Electricity is systemically important not because it is important in good times, but because it would be important in bad times. 
Ben Moll turned out to be right and Germany was able to substitute away from Russian Gas a lot more than people had thought, but even that proves the rule: if it is hard to substitute away from even a small input, then large shocks to that input imply larger expenditure shares and larger impacts on the economy than its small output in normal times would suggest.

There is an enormous amount more in the paper and voluminous appendices, but this is enough for a blog review. 

****

Now, a few limitations, or really thoughts on where we go next. (No more in this paper, please, Ian!) Ian does a nice illustrative computation of the sensitivity to large shocks:


Ian assumes \(\sigma>1\), so the main ingredients are how many downstream firms use your products and a bit their labor shares. No surprise, trucks, and energy have big tail impacts. But so do lawyers and insurance. Can we really not do without lawyers? Here I hope the next step looks hard at substitutes vs. complements.

That raises a bunch of issues. Substitutes vs. complements surely depends on time horizon and size of shocks. It might be easy to use a little less water or electricity initially, but then really hard to reduce more than, say, 80%. It's usually easier to substitute in the long run than the short run. 

The analysis in this literature is "static," meaning it describes the economy when everything has settled down.  The responses -- you charge more, I use less, I charge more, you use less of my output, etc. -- all happen instantly, or equivalently the model studies a long run where this has all settled down. But then we talk about responses to shocks, as in the pandemic.  Surely there is a dynamic response here, not just including capital accumulation (which Ian studies). Indeed, my hope was to see prices spreading out through a production network over time, but this structure would have all price adjustments instantly. Mixing production networks with sticky prices is an obvious idea, which some of the papers below are working on. 

In the theory and data handling, you see a big discontinuity. If a firm uses any inputs at all from another firm,  if \(A_{ij}>0\), that input can take over and drive everything. If it uses no inputs at all, then there is no network link and the upstream firm can't have any effect. There is a big discontinuity at \(A_{ij}=0.\) We would prefer a theory that does not jump from zero to everything when the firm buys one stick of chewing gum. Ian had to drop small but nonzero elements of the input-output matrix to produces sensible results. Perhaps we should regard very small inputs as always substitutes? 

How important is the network stuff anyway? We tend to use industry categorizations, because we have an industry input-output table. But how much of the US industry input-output is simply vertical: Loggers sell trees to mills who sell wood to lumberyards who sell lumber to Home Depot who sells it to contractors who put up your house? Energy and tools feed each stage, but don't use a whole lot of wood to make those. I haven't looked at an input-output matrix recently, but just how "vertical" is it? 

****

The literature on networks in macro is vast. One approach is to pick a recent paper like Ian's and work back through the references. I started to summarize, but gave up in the deluge. Have fun. 

One way to think of a branch of economics is not just "what tools does it use?" but "what questions is it asking?  Long and Plosser "Real Business Cycles," a classic, went after idea that the central defining feature of business cycles (since Burns and Mitchell) is comovement. States and industries all go up and down together to a remarkable degree. That pointed to "aggregate demand" as a key driving force. One would think that "technology shocks" whatever they are would be local or industry specific. Long and Plosser showed that an input output structure led idiosyncratic shocks to produce business cycle common movement in output. Brilliant. 

Macro went in another way, emphasizing time series -- the idea that recessions are defined, say, by two quarters of aggregate GDP decline, or by the greater decline of investment and durable goods than consumption -- and in the aggregate models of Kydland and Prescott, and the stochastic growth model as pioneered by King, Plosser and Rebelo, driven by a single economy-wide technology shock.  Part of this shift is simply technical: Long and Plosser used analytical tools, and were thereby stuck in a model without capital, plus they did not inaugurate matching to data. Kydland and Prescott brought numerical model solution and calibration to macro, which is what macro has done ever since.  Maybe it's time to add capital, solve numerically, and calibrate Long and Plosser (with up to date frictions and consumer heterogeneity too, maybe). 

Xavier Gabaix (2011)  had a different Big Question in mind: Why are business cycles so large? Individual firms and industries have large shocks, but \(\sigma/\sqrt{N}\) ought to dampen those at the aggregate level. Again, this was a classic argument for aggregate "demand" as opposed to "supply."  Gabaix notices that the US has a fat-tailed firm distribution with a few large firms, and those firms have large shocks. He amplifies his argument via the Hulten mechanism, a bit of networkyiness, since the impact of a firm on the economy is sales / GDP,  not value added / GDP. 

The enormous literature since then  has gone after a variety of questions. Dew-Becker's paper is about the effect of big shocks, and obviously not that useful for small shocks. Remember which question you're after.

My quest for a new Phillips curve in production networks is better represented by Elisa Rubbo's "Networks, Phillips curves and Monetary Policy," and Jennifer La'o and  Alireza Tahbaz-Salehi's “Optimal Monetary Policy in Production Networks,” If I can boil those down for the blog, you'll hear about it eventually.  

The "what's the question" question is doubly important for this branch of macro that explicitly models heterogeneous agents and heterogenous firms. Why are we doing this? One can always represent the aggregates with a social welfare function and an aggregate production function. You might be interested in how aggregates affect individuals, but that doesn't change your model of aggregates. Or, you might be interested in seeing what the aggregate production or utility function looks like -- is it consistent with what we know about individual firms and people? Does the size of the aggregate production function shock make sense? But still, you end up with just a better (hopefully) aggregate production and utility function. Or, you might want models that break the aggregation theorems in a significant way; models for which distributions matter for aggregate dynamics, theoretically and (harder) empirically. But don't forget you need a reason to build disaggregated models. 

Expression (1) is not easy to get to. I started reading Ian's paper in my usual way:  to learn a literature start with the latest paper and work backward. Alas, this literature has evolved to the point that authors plop results down that "everybody knows" and will take you a day or so of head-scratching to reproduce. I complained to Ian, and he said he had the same problem when he was getting in to the literature! Yes, journals now demand such overstuffed papers that it's hard to do, but it would be awfully nice for everyone to start including ground up algebra for major results in one of the endless internet appendices.  I eventually found Jonathan Dingel's notes on Dixit Stiglitz tricks, which were helpful. 

Update:

Chase Abram's University of Chicago Math Camp notes here  are also a fantastic resource. See Appendix B starting p. 94 for  production network math. The rest of the notes are also really good. The first part goes a little deeper into more abstract material than is really necessary for the second part and applied work, but it is a wonderful and concise review of that material as well. 


Rabu, 24 Mei 2023

Hoover Monetary Policy Conference Videos

The videos from the Hoover Monetary Policy Conference are now online here.  See my previous post for a summary of the conference. 

The big picture is now clearer to me. Phil Jefferson rightly asked, what do you mean off track? Monetary policy is doing fine. Interest rates are, in his view, where they should be. He argued the case well. 

But now I have an answer: The Fed has had three significant institutional failures: 1) Its inflation target is 2%, yet inflation exploded to 8%. The Fed did not forecast it, and did not see it even as it was happening. (Nor did many other forecasters, pointing to deeper conceptual problems.) 2) In the SVB and subsequent mess, the Fed's regulatory apparatus did not see or do anything about plain vanilla interest-rate risk combined with uninsured deposits. 3) I add a third, that nobody else seems to complain about: In 2020 starting with treasury markets, moving on to money market funds, state and local financing,  and then an astonishing "whatever it takes" that corporate bond prices shall not fall, the Fed already revealed that the Dodd-Frank machinery was broken. (Will commercial real estate be next?) 

Yet there is very little appetite for self-examination or even external examination. How did a good institution, filled with good, honest, smart and devoted public servants fail so badly? That's not "off-track" that's a derailment. 

Well, two sessions at the conference begin to ask those questions, and the others aimed at the same issues. Hopefully they will prod the Fed to do so as well, or at least to be interested in other's answers to those questions. 

(My minor contributions: on why the Taylor rule is important here, where I think I did a pretty good job; and comments on why inflation forecasts went so wrong at  1:00:16 here.)

Selasa, 16 Mei 2023

Hoover Monetary Policy Conference

Friday May 12 we had the annual Hoover monetary policy conference. Hoover twitter stream here.  Conference webpage and schedule here (update 5/24 now contains videos.) As before, the talks, panels, and comments will eventually be written and published. 

The Fed has experienced two dramatic institutional failures: Inflation peaking at 8%, and a rash of bank failures. There were panels focused on each, and much surrounding discussion.  

We started with a little celebration of the 30th anniversary of Taylor (1993), which put the Taylor rule on the map. As Andy Levin pointed out in the discussion, academic immortality comes when they omit the number after your name. Rich Clarida, Volker Weiland and I quickly outlined some academic influence. John Lipsky added some very interesting commentary on how the Taylor rule was important on Wall Street, and specifically from his experience at Salomon Bros. 

The second panel on financial regulation was a smash. Anat Admati chaired, with presentations by Darrell Duffie, Randy Quarles, and Amit Seru. 

Duffie showed how online banking has taken over, and the combination of twitter and online banking makes runs happen much faster than before. You don't have to stand in line, you can all push "withdraw" at once. He also showed a glaring hole in liquidity regulations: A bank cannot count as liquidity its ability to use the discount window at the Fed. 

Seru covered some of his recent work, showing just how many banks have lost 10% or more of their asset value, and thus the value of their equity. (Nobody mentioned commercial real estate, the next shoe to drop.) They gently disagreed, Darrel viewing more liquidity and better liquidity rules as the main solution, and Amit more equity. All seemed to agree that the current regulatory mechanism is fundamentally broken. 

Randy gave a thoughtful, eloquent, and impassioned talk laying to rest the common notion that "deregulation" caused SVB to fail. It would have passed all the stress tests. This will be important to read when the papers are all available. I take the implication that the regulatory structure is, again, fundamentally broken. No, more of the current regulations would not have helped. But Randy didn't say that. 

Peter Henry next presented "Disinflation and the Stock Market: Third World Lessons for First World Monetary Policy" (a paper with Anusha Chari), discussed by Josh Rauh and Chaired by Bill Nelson. A key innovation, they use stock market reactions to measure whether disinflations are a success on a cost/benefit basis. Large inflations seem to end with stock market expansions. Moderate disinflations don't really do much for stock markets. Most disinflationary reforms fail.

Over lunch, Haruhiko Kuroda, Former Governor, Bank of Japan updated us on the Japanese situation. He is confident 2% inflation will return soon. 

Niall Ferguson and Paul Schmelzing presented "The Safety Net: Central Bank Balance Sheets and Financial Crises 1587-2020," (with Martin Kornejew and Moritz Schularick), with Barry Eichengreen discussing and Michael Bordo chair. A taste: 


The paper concludes that lender of last resort operations do work, and also create moral hazard. Barry had an eloquent discussion, noting among other things that not all balance sheet expansions are the same. Look for those in the written versions. 

Next, Mickey Levy presented The Fed: Bad Forecasts and Misguided Monetary Policy, Steve Davis discussing and  Jim Wilcox chair. The Fed -- and most industry analysts -- completely missed 8% inflation, both ahead of time and as it was happening. Why? How can the Fed do better? (And why is the Fed not asking this question?) 


To me, it looks like the forecast is not much more than an AR(1) reversion to 2% inflation. The paper has a good summary of how Fed forecasts are made, along with recommendations for institutional improvement.  

Steve Davis had an excellent discussion, pointing to a central incentive problem. The Fed uses forecasts to try to shape expectations. Like pubic health authorities, it can be afraid to reveal actual fears. I also see conceptual flaws -- not much attention to supply or fiscal policy, using the Phillips curve as a causal model and as a model in itself, too much attention to the one-period link from expected inflation to inflation, and too much attention to the forecast rather than risk management; what do we do if things come out differently. 

The conference day ended with the traditional policy panel, with Jim Bullard (talk here), Philip Jefferson (talk here), Jeff Lacker, and Charlie Plosser, Chaired by John Taylor. 

Bullard pointed to the huge fiscal stimulus as a source of inflation, warming my heart. He opined that this stimulus is fading, making him hopeful for a soft landing. He presented the following chart. 

This is a very interesting measure of how much "stimulus" is sitting out there in the economy. The government did write a lot of checks, that went straight to people's bank accounts, and eventually were spent, driving up inflation. On the other hand, I am still a bit shocked that we're running $1 trillion deficit despite beyond-full employment and output revving at every bit that the "supply" side of the economy can produce. What's your measure of fiscal stimulus? Which forecasts inflation? This is a very provocative and interesting idea. 

Jefferson gave a great talk. He has the measured cadence of a seasoned central banker, but speaks very clearly and directly.  He started by announcing his appointment as vice-chair, which got a well deserved ovation. He then jumped right in: 
The title of the conference "How to Get Back on Track: A Policy Conference" is potent. Its intent and ambiguity are striking. First, the title presupposes that U.S. monetary policy is currently on the wrong track. Second, the webpage for this conference advances a puzzling definition of the phrase "on track." How so? According to the Hoover webpage, "A key goal of the conference is to examine how to get back on track and, thereby, how to reduce the inflation rate without slowing down economic growth" (emphasis added).1 As this audience knows, there are macroeconomic models that permit disinflation with no slowdown in economic growth, but the assumptions underlying these models are very strong. It's not clear, at least to me, why such a strict metric would be used to assess real-world monetary policymaking....

I loved this. It shows he took the time to read up on the conference, and I love seeing basic premises challenged. Later, this struck me as thoughtful: 

I want to share with you a few strategic principles that are important to me. First, policymakers should be ready to react to a wide range of economic conditions with respect to inflation, unemployment, economic growth, and financial stability. The unprecedented pandemic shock is a good reminder that under extraordinary circumstances it will be difficult to formulate precise forecasts in real time. Our dual mandate from the Congress is especially helpful here. It provides the foundation for all our policy decisions. Second, policymakers should clearly communicate monetary policy decisions to the public. Our commitment to transparency should be evident to the public, and monetary policy should be conducted in a way that anchors longer-term inflation expectations. Third—and this is where I am revealing my passion for econometrics—policymakers should continuously update their priors about how the economy works as new data become available. In other words, it is appropriate to change one's perspective as new facts emerge. In this sense, I am in favor of a Bayesian approach to information processing.

The first point brings us back to the problem that the Fed has so far been too silent about: How did it miss 8% inflation? And how to operate when such huge misses are possible? The Fed seems to have been making a forecast, then announcing a policy path that works for the forecast, and then trying to stick to it. In this first principle you see a quite different view. Let's call it data-dependent rather than time-dependent. 

This is a conference about the Taylor rule. Should the Fed look at more than inflation and employment? Well, yes and no according to these comments. And when models are not certain, distrust and update.

Plosser and Lacker previewed an upcoming paper on the Fed's deviation from rules. Stay tuned. 

The evening started with a delightful speech by Sebastian Edwards on Latin American inflation. Stay tuned for that too. 

Videos should be up soon, and written versions as fast as we can get authors to turn them in. This is just a teaser!  

Update: Videos are now up, with some more commentary here.


Senin, 15 Mei 2023

FTPL 50% off sale

Princeton University Press has a 50% off sale on all books, including the (overpriced, sorry) Fiscal Theory of the Price Level.  The splash page also offers 30% off if you give them your email, but I'm not sure if they add. 

Kamis, 20 April 2023

How do interest rates lower inflation?


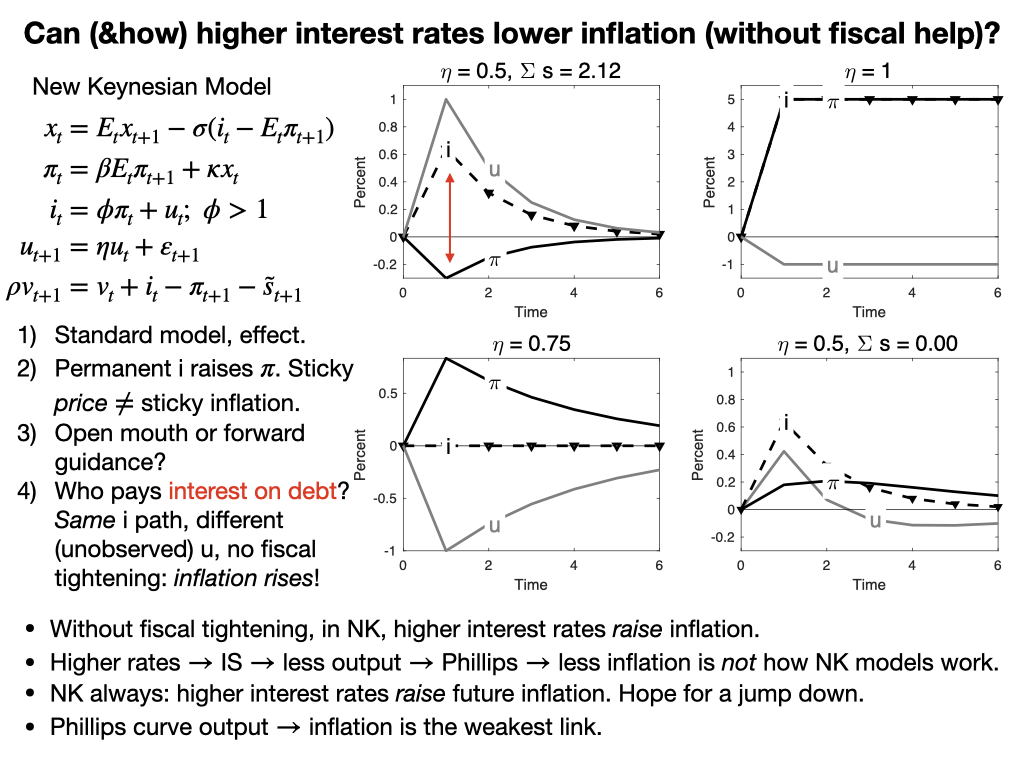
A few days ago I gave a short talk on the subject. I was partly inspired by a little comment made at a seminar, roughly "of course we all know that if prices are sticky, higher nominal rates raise higher real rates, that lowers aggregate demand and lowers inflation." Maybe we "know" that, but it's not as readily present in our models as we think. This also crystallizes some work in the ongoing "Expectations and the neutrality of interest rates" project. 

The equations are the utterly standard new-Keynesian model. The last equation tracks the evolution of the real value of the debt, which is usually in the footnotes of that model. 

OK, top right, the standard result. There is a positive but temporary shock to the monetary policy rule, u. Interest rates go up and then slowly revert. Inflation goes down. Hooray. (Output also goes down, as the Phillips Curve insists.) 

The next graph should give you pause on just how you interpreted the first one. What if the interest rate goes up persistently? Inflation rises, suddenly and completely matching the rise in interest rate! Yet prices are quite sticky -- k = 0.1 here. Here I drove the persistence all the way to 1, but that's not crucial. With any persistence above 0.75, higher interest rates give rise to higher inflation. 

What's going on? Prices are sticky, but inflation is not sticky. In the Calvo model only a few firms can change price in any instant, but they change by a large amount, so the rate of inflation can jump up instantly just as it does. I think a lot of intuition wants inflation to be sticky, so that inflation can slowly pick up after a shock. That's how it seems to work in the world, but sticky prices do not deliver that result. Hence, the real interest rate doesn't change at all in response to this persistent rise in nominal interest rates.  Now maybe inflation is sticky, costs apply to the derivative not the level, but absolutely none of the immense literature on price stickiness considers that possibility or how in the world it might be true, at least as far as I know. Let me know if I'm wrong. At a minimum, I hope I have started to undermine your faith that we all have easy textbook models in which higher interest rates reliably lower inflation. 

(Yes, the shock is negative. Look at the Taylor rule. This happens a lot in these models, another reason you might worry. The shock can go in a different direction from observed interest rates.) 

Panel 3 lowers the persistence of the shock to a cleverly chosen 0.75. Now (with sigma=1, kappa=0.1, phi= 1.2), inflation now moves with no change in interest rate at all.  The Fed merely announces the shock and inflation jumps all on its own. I call this "equilibrium selection policy" or "open mouth policy." You can regard this as a feature or a bug. If you believe this model, the Fed can move inflation just by making speeches! You can regard this as powerful "forward guidance." Or you can regard it as nuts. In any case, if you thought that the Fed's mechanism for lowering inflation is to raise nominal interest rates, inflation is sticky, real rates rise, output falls and inflation falls, well here is another case in which the standard model says something else entirely. 

Panel 4 is of course my main hobby horse these days. I tee up the question in Panel 1 with the red line. In that panel, the nominal interest are is higher than the expected inflation rate. The real interest rate is positive. The costs of servicing the debt have risen. That's a serious effect nowadays. With 100% debt/GDP each 1% higher real rate is 1% of GDP more deficit, $250 billion dollars per year. Somebody has to pay that sooner or later. This "monetary policy" comes with a fiscal tightening. You'll see that in the footnotes of good new-Keynesian models: lump sum taxes come along to pay higher interest costs on the debt. 

Now imagine Jay Powell comes knocking to Congress in the middle of a knock-down drag-out fight over spending and the debt limit, and says "oh, we're going to raise rates 4 percentage points. We need you to raise taxes or cut spending by $1 trillion to pay those extra interest costs on the debt." A laugh might be the polite answer. 

So, in the last graph, I ask, what happens if the Fed raises interest rates and fiscal policy refuses to raise taxes or cut spending? In the new-Keynesian model there is not a 1-1 mapping between the shock (u) process and interest rates. Many different u produce the same i. So, I ask the model, "choose a u process that produces exactly the same interest rate as in the top left panel,  but needs no additional fiscal surpluses." Declines in interest costs of the debt (inflation above interest rates) and devaluation of debt by period 1 inflation must match rises in interest costs on the debt (inflation below interest rates). The bottom right panel gives the answer to this question. 

Review: Same interest rate, no fiscal help? Inflation rises. In this very standard new-Keynesian model,  higher interest rates without a concurrent fiscal tightening raise inflation, immediately and persistently. 

Fans will know of the long-term debt extension that solves this problem, and I've plugged that solution before (see the "Expectations" paper above).

The point today: The statement that we have easy simple well understood textbook models, that capture the standard intuition -- higher nominal rates with sticky prices mean higher real rates, those lower output and lower inflation -- is simply not true. The standard model behaves very differently than you think it does. It's amazing how after 30 years of playing with these simple equations, verbal intuition and the equations remain so far apart. 

The last two bullet points emphasize two other aspects of the intuition vs model separation. Notice that even in the top left graph, higher interest rates (and lower output) come with rising inflation. At best the higher rate causes a sudden jump down in inflation -- prices, not inflation, are sticky even in the top left graph -- but then inflation steadily rises. Not even in the top left graph do higher rates send future inflation lower than current inflation. Widespread intuition goes the other way. 

In all this theorizing, the Phillips Curve strikes me as the weak link. The Fed and common intuition make the Phillips Curve causal: higher rates cause lower output cause lower inflation. The original Phillips Curve was just a correlation, and Lucas 1972 thought of causality the other way: higher inflation fools people temporarily to producing more. 


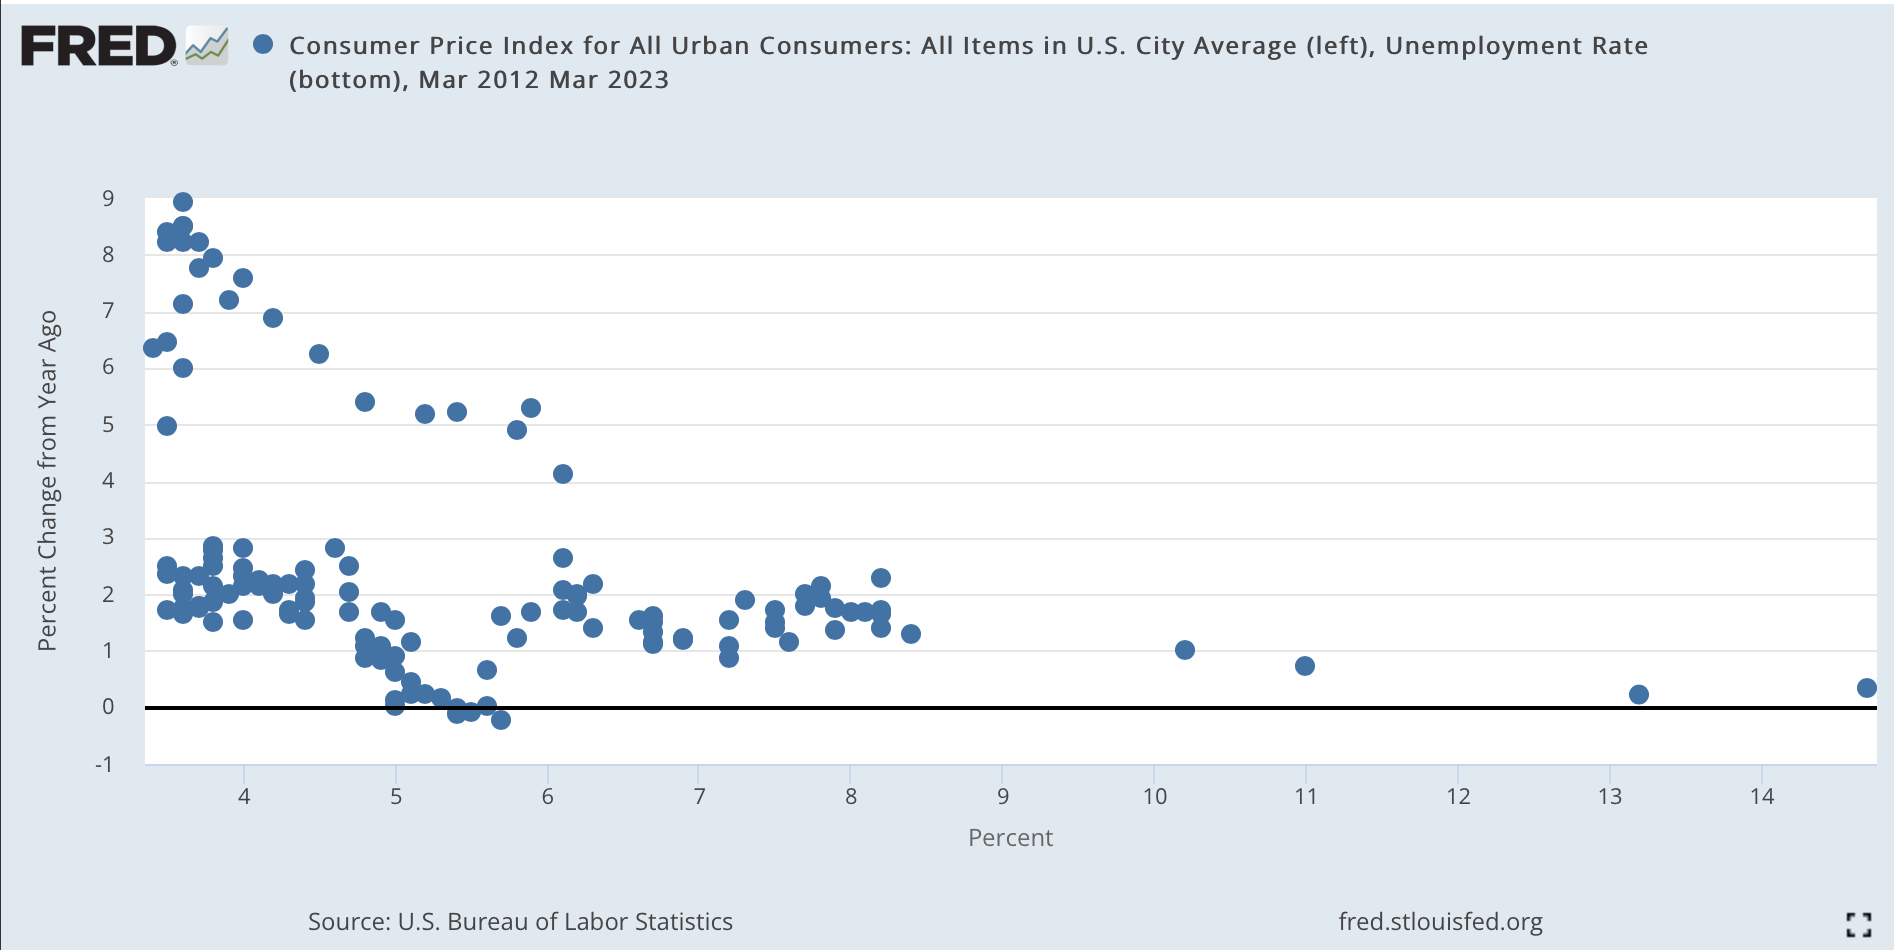
Here is the Phillips curve (unemployment x axis, inflation y axis) from 2012 through last month. The dots on the lower branch are the pre-covid curve, "flat" as common wisdom proclaimed. Inflation was still 2% with unemployment 3.5% on the eve of the pandemic. The upper branch is the more recent experience. 

I think this plot makes some sense of the Fed's colossal failure to see inflation coming, or to perceive it once the dragon was inside the outer wall and breathing fire at the inner gate. If you believe in a Phillips Curve, causal from unemployment (or "labor market conditions") to inflation, and you last saw 3.5% unemployment with 2% inflation in February 2021, the 6% unemployment of March 2021 is going to make you totally ignore any inflation blips that come along. Surely, until we get well past 3.5% unemployment again, there's nothing to worry about. Well, that was wrong. The curve "shifted" if there is a curve at all. 

But what to put in its place? Good question. 

Update:

Lots of commenters and correspondents want other Phillips Curves. I've been influenced by a number of papers, especially "New Pricing Models, Same Old Phillips Curves?" by Adrien Auclert, Rodolfo Rigato, Matthew Rognlie, and Ludwig Straub, and "Price Rigidity: Microeconomic Evidence and Macroeconomic Implications" by Emi Nakamura and  Jón Steinsson, that lots of different micro foundations all end up looking about the same. Both are great papers. Adding lags seems easy, but it's not that simple unless you overturn the forward looking eigenvalues of the system; "Expectations and the neutrality of interest rates" goes on in that way. Adding a lag without changing the system eigenvalue doesn't work. 

Kamis, 02 Maret 2023

Lessons from Sargent and Leeper

At the AEI fiscal theory event last Tuesday Tom Sargent and Eric Leeper made some key points about the current situation, with reference to lessons of history. 

Tom's comments updated his excellent paper with George Hall "Three World Wars" (at pnas,  summary essay in the Hoover Conference volume). Tom and George liken covid to a war: a large emergency requiring immense expenditure. We can quibble about "require" but not the expenditure. 


(2008 was a little war in this sense as well.) Since outlays are well ahead of receipts, these huge temporary expenditures are financed by issuing debt and printing money, as optimal tax theory says they should be. 

In all three cases, you see a ratcheting up of outlays after the war. That's happening now, and in 2008, just as in WWI and WWII. 

After WWI and WWII, there is a period of primary surpluses -- tax receipts greater than spending -- which helps to pay back the debt. This time is notable for the absence of that effect. 


We see that most clearly by plotting the primary deficits directly. The data update since Tom and George's original paper (dots) makes that clear. To a fiscal theorist, this is a worrisome difference. We are not following historical tradition of regular, full employment, peacetime surpluses. 


The two world wars were also financed by a considerable inflation. The important consequence of inflation is that it inflates away government debt. Essentially, we pay for part of the war by a default on debt, engineered via inflation. 

1947 is an interesting case. As now, inflation broke out, the Fed left interest rates alone, and the inflation went away once it had inflated away enough debt. That too is an interesting episode in the debate whether the Fed must move rates more than one for one to keep inflation from spiraling away. 

The effect of inflation is clearer in the next graph, which plots the real return on government bonds: 


Yes, the inflation of 1920 did inflate away a lot of the WWI debt, though the deflation of 1921 brought a lot of that back. (This is an episode we would do well to remember more! The price level doubled from 1916 through 1920. It then retreated by a third in 1920-1921. There was a sharp recession, but the economy recovered very quickly with no stimulus or heroic measures. The conventional wisdom that wringing out WWI inflation caused the UK 1920s doldrums needs to consider this counterexample. But back to our point) 

This is also consistent with standard optimal tax theory, which says that in the event of a disaster that happens once every 50 years or so, it is right to execute a "state contingent default" (Lucas and Stokey), and inflation is a natural way to do it. 

But... "state contingent default" is supposed to happen at the beginning of a war. These inflations happened at the end of the war. How did governments sell bonds to people who should have expected them to be inflated away? Yes, there were some price controls and financial repression, but it's still an important puzzle to standard public finance theory.  

My concern, of course, is that we've had two once in a hundred year events in a row (2008, 2020), I can think of lots more that might come soon, and you can only do this occasionally. Hit people over the head a few too many times and they start to duck. We will head to the next crisis with no history of steady surpluses in good times, 100% debt to GDP ratio, and a painful reminder of what happens if you lend to the US right in the rear view mirror. 


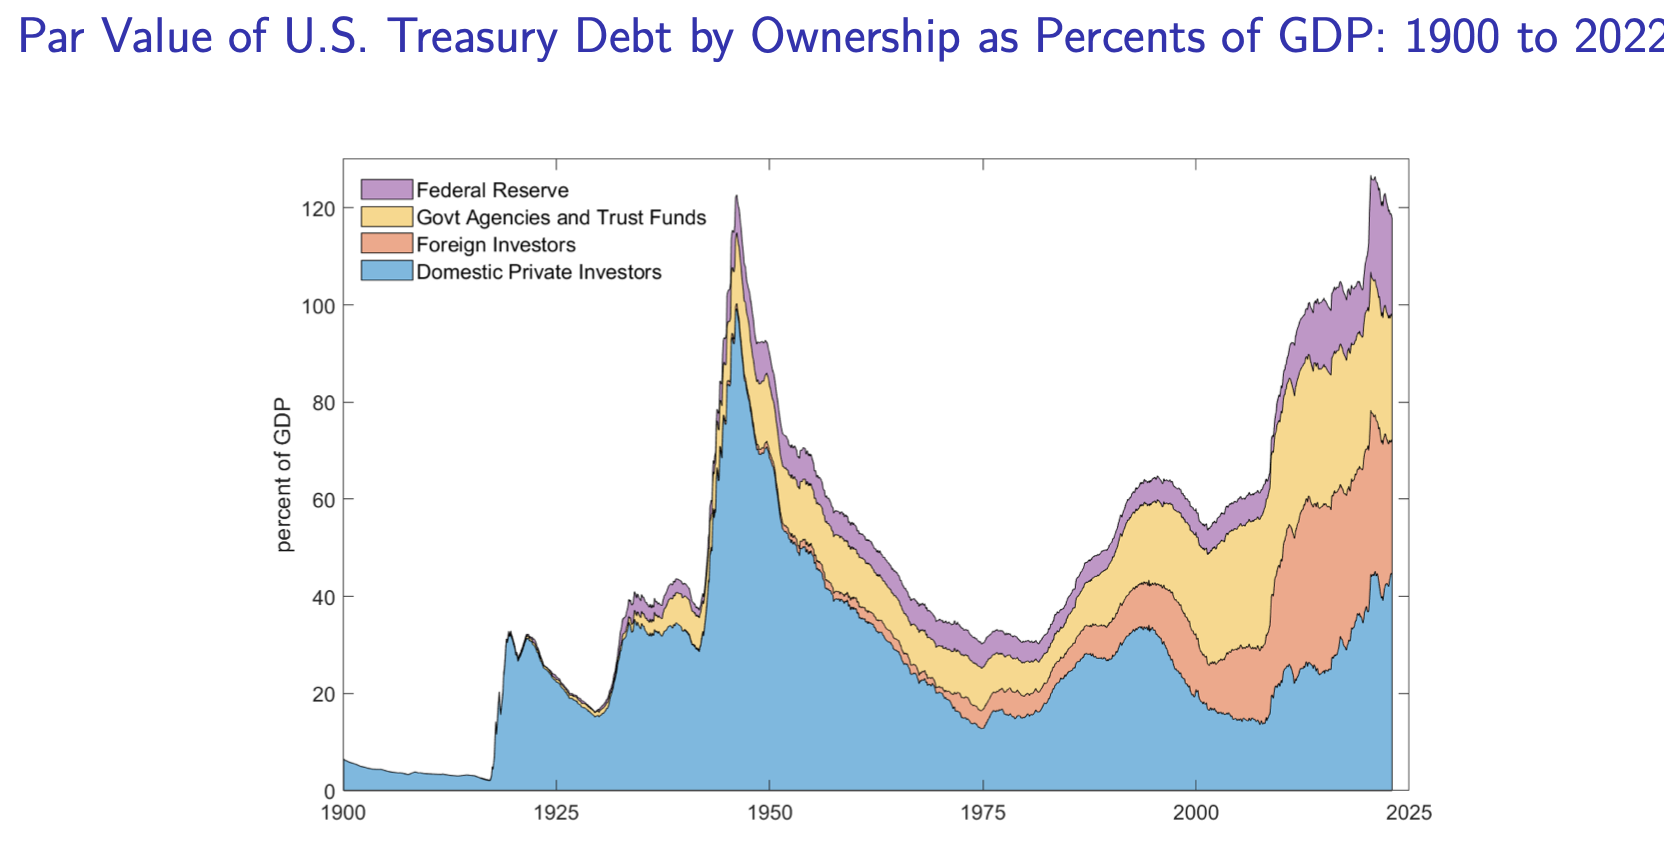
We start the H5N1/Taiwan war crisis with the same debt we had at the end of WWII. And who owns the debt leads to some fascinating speculation which I'll let you fill in with your chat GPT.  

Tom closed by echoing my favorite bright idea for avoiding the debt limit: Since the limit applies to par value not market value, the Treasury can issue all the perpetuities it wants. That's far better than the trillion dollar coin, though I suspect the Supreme Court would take just as dim a view of it. 

Eric  brought up a great point from his super Recovery of 1933 paper with Margaret Jacobson and Bruce Preston. 
In 1933, we had a disastrous deflation. The gold standard is a lovely fiscal commitment device to try to contain inflation, but it has an Achilles heel. If there is a deflation, the government has to raise taxes to pay an unexpected real windfall to bondholders. In 1933, the Roosevelt Administration abrogated the gold standard. It was a default on the legal terms of the bonds. And look what happened to inflation! 

Eric also brought up a second central point of his 1933 paper: The Roosevelt Administration separated the budget into a "regular" budget, in which we should expect deficits to be paid back, and an "emergency" budget, unbacked (in our language) by expected surpluses. That cleverly allowed inflationary finance in 1933, but once the "emergency" was over in 1941, it preserved the US reputation for repaying wartime debts with subsequent surpluses, and allowed it to borrow for WWII. This loss of "back to normal," of expectations that we are now in "regular" not "emergency" finance is worrisome today. 

Finally, Eric brought some nice evidence to bear on the question, why 2020 but not 2008? Well, in part, we can look at statements of public officials. In 2008, they explicitly said, deficit now, repayment later. In 2020 they explicitly said the opposite. 

("Offsets" is Washington-speak for "taxes" or later spending cuts.) Don't read a pejorative in this analysis. If you want to borrow, finance crisis expenditures and not create inflation, you "maintain the norm." If you want to create a "state contingent default" and pay for crisis expenditures by inflating away debt, you have to "violate the norm." That is darn hard -- ask the Japanese. How do you convince people you're not going to repay some part of the debt, despite a good reputation, but just some part, and if WWII comes along you're good for additional debts? Well, announcing your intentions helps!  


And it worked. We very quickly inflated away the debt. Creating a state contingent default via inflation is not easy. Still to be seen though is whether we can return to "normal" "Hamilton norm" once it's over. 

Robert Barro also had great comments, but more directed at the book and with no great graphs to pass along. Thanks anyway!

Fiscal inflation and interest rates

Economics is about solving lots of little puzzles. At a July 4th party, a super smart friend -- not a macroeconomist -- posed a puzzle I sho...